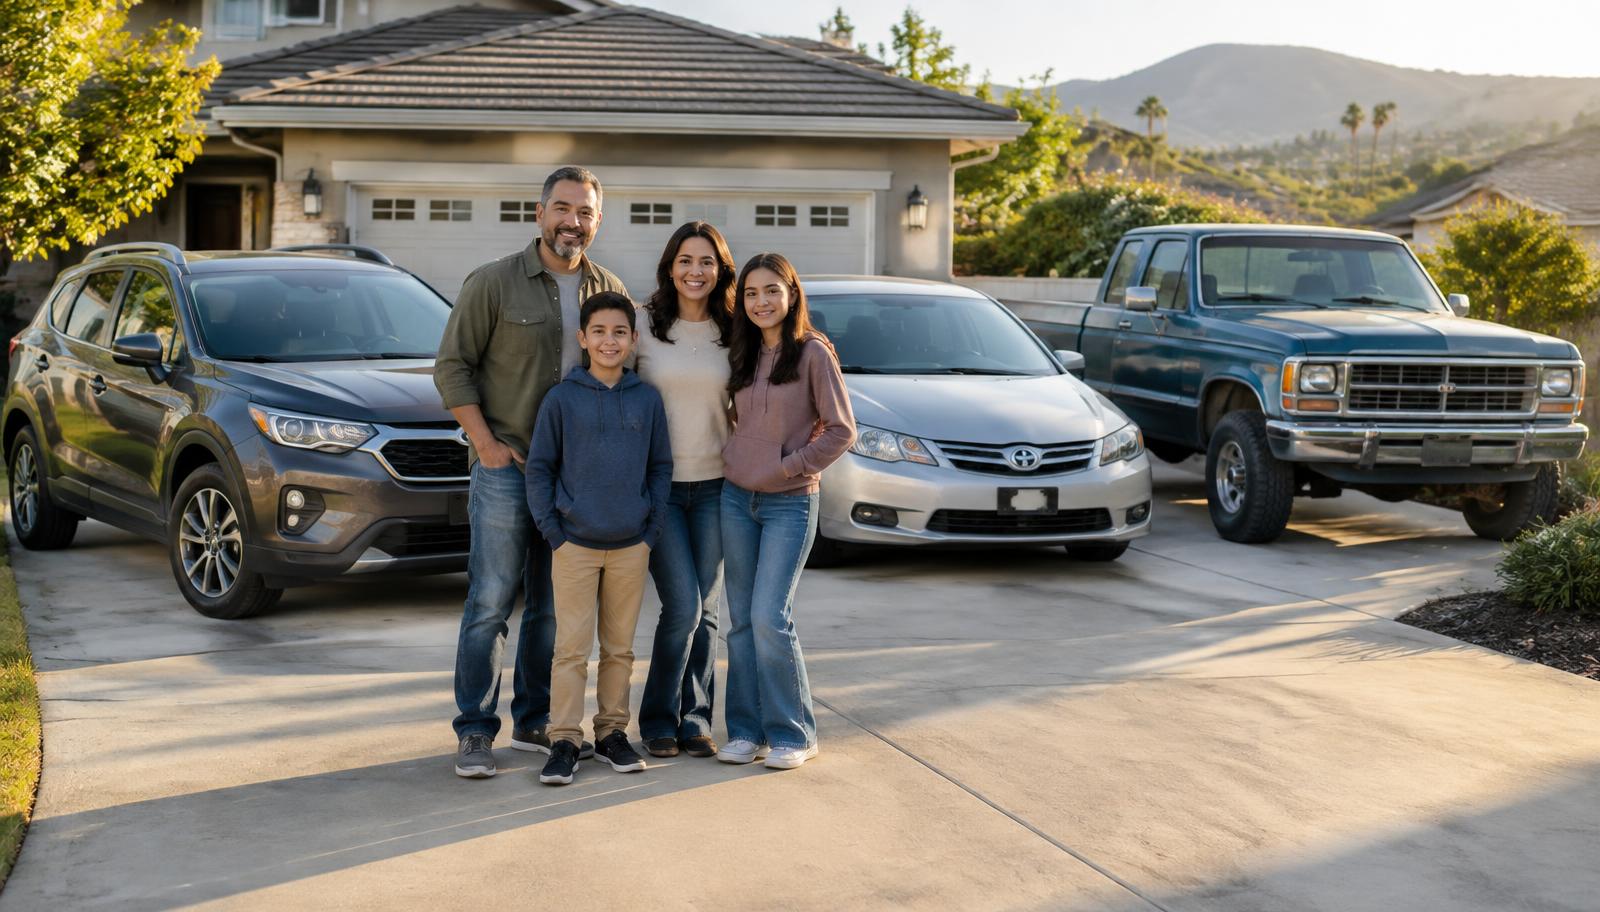
Most households in El Cajon do not run on a single car. Between work commutes, school drop-offs, weekend errands, and a teenager who just got a license, two or three vehicles in the driveway is common. How you insure those vehicles matters more than many people realize.
A multi-car policy is not just a convenience. It can save money, simplify paperwork, and help make sure every vehicle and driver in your household is properly accounted for. It also comes with details that are easy to overlook. At Vetra Insurance, we help El Cajon families compare multi-vehicle policies built around the whole household, not just the primary driver.
What Is a Multi-Car Policy?
A multi-car policy covers two or more vehicles under one insurance policy, generally with one policy number, renewal date, and declarations package. Instead of managing separate policies for each vehicle with different carriers, renewal dates, and billing cycles, coverage is consolidated.
Many California insurance carriers offer discounts for insuring more than one eligible vehicle together. The amount varies by carrier, number of vehicles, drivers, coverage selections, and other rating factors. Your agent can compare the total household cost rather than focusing on one vehicle at a time.
Who Needs to Be Listed on the Policy?
Insurance companies generally ask about every licensed or permitted driver who lives in your household, even if someone only occasionally drives your vehicles. Requirements vary by insurer, so it is important to answer household-driver questions accurately.
This may include a spouse or domestic partner, adult children living at home, other relatives or roommates who share your address, and teen drivers with a learner's permit or provisional license.
Not every person must be the primary driver of a specific vehicle, but the insurer needs an accurate picture of who has access to the cars. Failing to disclose a household driver can create complications after an accident and may affect coverage. List household drivers honestly, then work with your agent to review how the insurer rates each person and vehicle.
How Drivers and Vehicles Affect the Rate
When a policy includes several vehicles and drivers, the insurer evaluates the household using its own rating rules. A driver's experience, driving record, annual mileage, vehicle use, and the characteristics of each car can all affect the premium.
For example, a household with an experienced driver and a newly licensed teen may pay less when the teen primarily uses an older, lower-value vehicle with strong safety features rather than the newest vehicle. The result depends on the carrier's rules, and drivers should always be listed according to how the vehicles are actually used.
An independent agent can compare carriers and explain how each company evaluates the household. That is one practical advantage of working with an agent instead of relying only on a simplified online quote form.
Coverage Does Not Have to Be Identical Across Vehicles
One useful feature of many multi-car policies is the ability to customize physical-damage coverage and deductibles for each vehicle. Liability limits usually apply consistently across the policy, while collision and comprehensive choices can often differ by car.
A new financed SUV may need comprehensive and collision coverage because the lender requires it and the vehicle's value supports the protection. A paid-off sedan used for short trips might carry different deductibles or omit collision after the owner weighs the premium against the car's current value. An older weekend truck may need a different combination again.
This flexibility can help you direct coverage where it matters most. Any financed or leased vehicle must meet the lender's requirements, and reducing physical-damage coverage means accepting more financial risk if that vehicle is damaged.
Adding and Removing Vehicles During the Year
Households change. You buy a car, a teenager gets a vehicle, you sell a truck, or a college student takes a car to campus.
With a multi-car policy, these changes are usually handled as adjustments to one policy. Contact your agent before or immediately after a change and confirm the exact effective date in writing. Do not assume a newly purchased vehicle is covered without checking the policy's terms and notifying the insurer within its required timeframe.
When a vehicle is removed, any premium adjustment, refund, or account credit depends on the carrier, timing, and policy terms. Keep insurance active until ownership has transferred and the vehicle is no longer registered to you.
Some carriers offer a distant-student discount when an eligible student attends school away from home and has limited access to household vehicles. Eligibility and distance requirements vary. If a student takes a car to school, tell the insurer where the vehicle will be kept and driven.
Common Multi-Car Scenarios in El Cajon
The two-car commuter household. Both partners drive to work, perhaps one heading into San Diego on Interstate 8 and the other working locally in El Cajon. Both financed vehicles carry lender-required coverage. A multi-car discount may reduce the total premium, and combining auto with homeowners coverage may create additional savings.
The family with a new teen driver. Three vehicles and three drivers can produce a noticeable premium increase. Good-student discounts, safe-driving programs, vehicle choice, and careful carrier comparison may help manage the cost.
The household with a weekend vehicle. A daily driver, a commuter car, and an older truck or Jeep used occasionally may need different mileage estimates, deductibles, and physical-damage coverage. Tell the insurer how each vehicle is actually used.
The multigenerational household. Adult children and a retired parent may share two or three vehicles. Accurately listing drivers and vehicle use helps the carrier rate the risk correctly and reduces surprises if a claim occurs.
Mistakes Families Make With Multi-Car Policies
Not disclosing household drivers. If someone in your home has access to your vehicles and is not disclosed, you may create a coverage problem. Ask your agent how each licensed or permitted household member should be handled.
Carrying identical coverage on every vehicle. Each car has a different value and purpose. Review collision, comprehensive, deductibles, mileage, and lender requirements vehicle by vehicle.
Comparing only one car at a time. Vehicles insured separately may miss a multi-car discount. Compare the total price and protection for the entire household. Consolidating can help, but it is not automatically the least expensive choice in every case.
Misstating vehicle use. Rates should reflect who primarily drives each car, where it is garaged, annual mileage, and commuting use. Accurate information protects the integrity of the policy and claim process.
Forgetting changes. A child moving out, a vehicle being sold, or a family member no longer driving can affect the policy. Review coverage whenever the household changes, not only at renewal.
The Bundling Advantage
A multi-car discount may combine with savings for bundling auto insurance with homeowners, renters, or umbrella coverage. Some insurers also offer discounts connected to other eligible policies or safe-driving programs.
Discounts and eligibility differ by company. The best comparison looks at the final premium, deductibles, limits, exclusions, and service, not just the number of discounts shown on a quote. An independent agent can compare several carriers and help you understand the tradeoffs.
Build a Policy Around Your Whole Household
Every household is different, and a multi-car policy should reflect yours. Vetra Insurance looks at each vehicle, driver, commute pattern, coverage need, and budget before comparing options from multiple carriers.
Explore auto insurance in El Cajon, or request a free quote to review your current policies. You can also call Vetra Insurance at (619) 630-9091. We will help you compare options and protect every seat in every car.
Related coverage in El Cajon
Get a Free Auto Quote
Talk to a local Vetra Insurance agent in El Cajon. We compare 15+ A-rated carriers to find the right coverage for your situation.