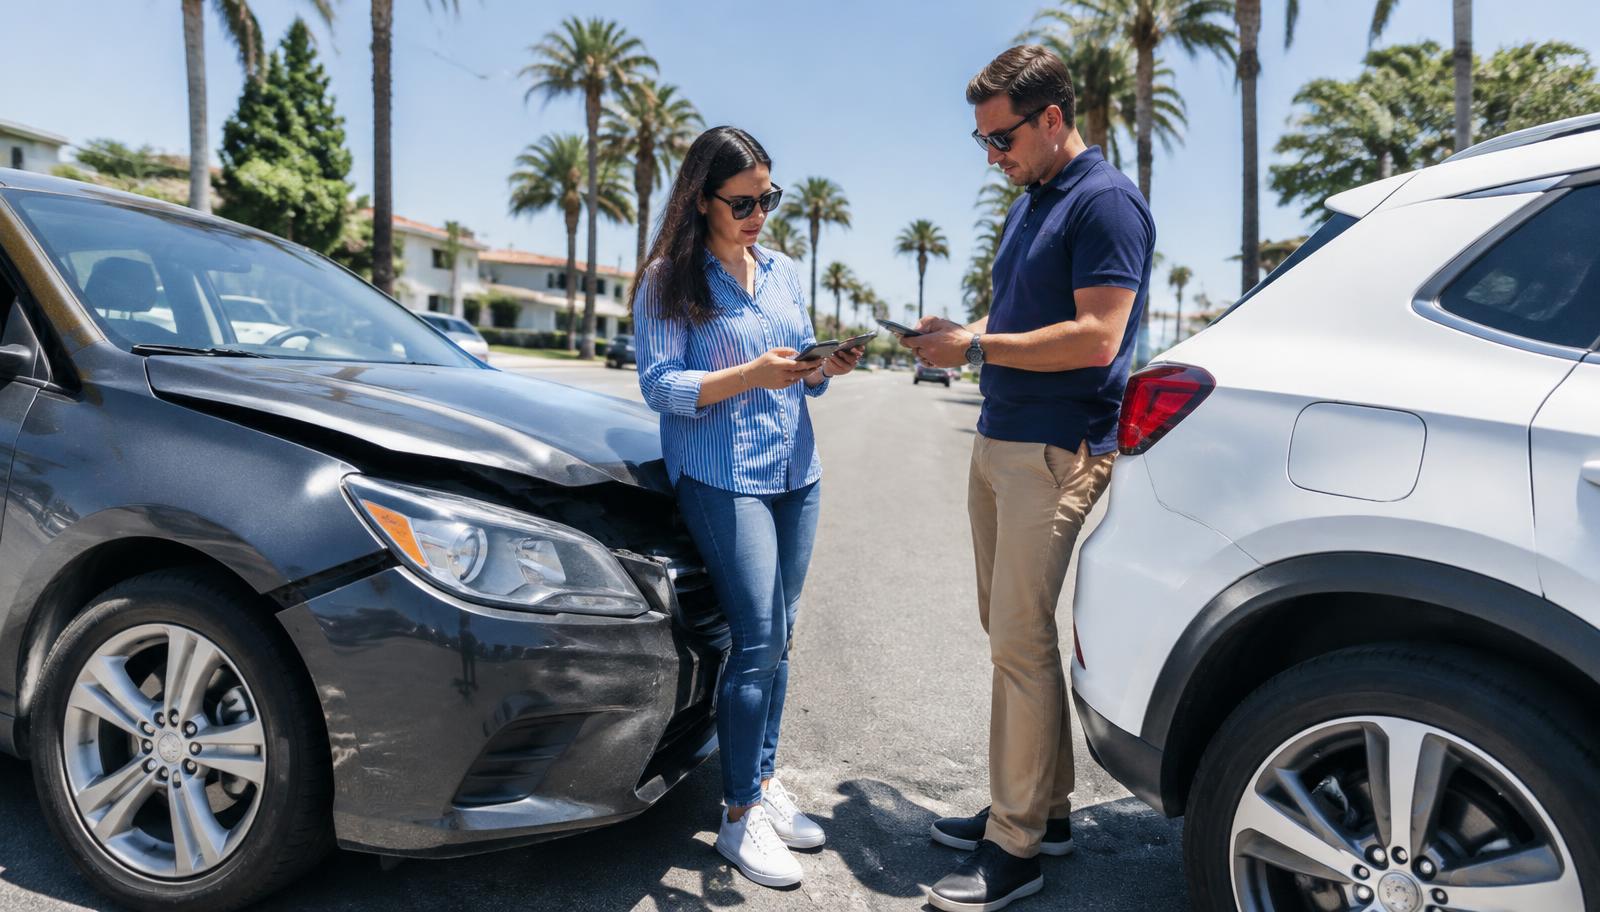
You just had an accident. Maybe it was a fender bender in the Vons parking lot on East Main. Maybe it was something more serious on the 8. Either way, once the adrenaline fades and the paperwork starts, the same question lands in the back of every driver's mind: how much is this going to raise my insurance?
The answer isn't as simple as most people think. Not every accident raises your rate. Not every rate increase is the same size. And there are things you can do, both before and after an accident, that affect how big the financial impact actually is. At Vetra Insurance, we help El Cajon drivers understand what's coming after an accident so they can make smart decisions instead of anxious ones.
Not Every Accident Raises Your Premium
The first thing to understand is that an accident on your record doesn't automatically mean a higher rate. Several factors determine whether your insurer will surcharge your premium, and the most important one is fault.
At-Fault vs. Not-at-Fault
California law prohibits insurance companies from raising your premium based on an accident where you were not at fault. If someone rear-ended you at a red light, ran a stop sign and hit your car, or sideswiped you while changing lanes, your insurer cannot surcharge you for that claim.
This protection comes from California Insurance Code Section 488 and the state's rating regulations. It means that filing a claim after a not-at-fault accident should not affect your rate, and if it does, you have the right to challenge it.
At-fault accidents are a different story. When you're determined to be the cause of an accident, your insurer will typically apply a surcharge at your next renewal. The size of that surcharge depends on the severity of the accident, your prior driving history, and your carrier's specific rating methodology.
The Severity Factor
Not all at-fault accidents are treated equally. A minor parking lot scrape with $1,500 in damage is viewed very differently from a multi-vehicle highway collision with injuries and a $50,000 claim payout.
Most carriers use a tiered approach. Small claims may result in a modest surcharge or, in some cases, no surcharge at all if the payout falls below a certain threshold. Larger claims with significant bodily injury or property damage will produce a more substantial rate increase.
The presence of injuries is usually the dividing line. An at-fault accident with injuries signals a higher level of risk to the insurer than a property-damage-only incident, and the premium impact reflects that difference.
How Much Can Your Rate Actually Go Up?
The size of a post-accident rate increase varies widely, but understanding the general range helps set expectations.
For a first at-fault accident with moderate damage and no injuries, many drivers see a premium increase in the range of twenty to forty percent. For a more serious accident involving injuries or a large payout, the increase can be fifty percent or more. A DUI-related accident, which combines a moving violation with a collision, often produces the steepest increases, sometimes doubling or tripling the premium.
These percentages apply to your total premium, not just one coverage type. A driver paying $2,000 annually who sees a thirty percent increase after an at-fault accident would pay approximately $2,600: an additional $600 per year, or $50 per month. Over the three to five years the surcharge remains on the policy, that adds up to $1,800 to $3,000 in additional premium.
This is one reason why filing a claim for minor damage that barely exceeds your deductible deserves careful thought. If your deductible is $1,000 and the repair costs $1,400, the $400 insurance payout might not be worth the potential rate increase over the following years. Your agent can help you think through the math before you file. Learn more about our auto insurance in El Cajon.
How Long Does an Accident Affect Your Rate?
In California, most at-fault accidents affect your insurance rate for three to five years from the date of the incident. The exact duration depends on your carrier and the nature of the accident.
During this period, the surcharge is applied at each renewal. It doesn't necessarily stay at the same level for the entire duration. Some carriers gradually reduce the surcharge as time passes without another incident, while others maintain a flat surcharge until the accident ages off your record entirely.
After the surcharge period ends, your rate should return to what it would have been without the accident, assuming no other changes to your driving record or risk profile. This is also an excellent time to shop your policy, because the carrier that was cheapest with an accident surcharge may not be the cheapest once the surcharge is removed.
DUI-related incidents tend to affect rates for a longer period, up to ten years with some carriers, which is one of the many reasons a DUI conviction carries such significant financial consequences beyond the legal penalties.
Accident Forgiveness: What It Is and How It Works
Accident forgiveness is a feature offered by many insurance carriers that prevents your first at-fault accident from triggering a rate increase. It's exactly what it sounds like: your insurer "forgives" one accident and keeps your premium where it was.
There are two common versions of this feature.
Earned accident forgiveness is awarded automatically after you've maintained a clean driving record with the carrier for a specified period, typically three to five years without an at-fault accident or major violation. You don't pay extra for it. It's a loyalty benefit.
Purchased accident forgiveness is an optional endorsement you add to your policy for an additional premium. You can buy it from the start of your policy without needing to earn it through years of clean driving.
A few important details about accident forgiveness that are often overlooked:
It typically applies to only one accident. If you have a second at-fault accident during the same policy period, the forgiveness has been used and the second accident will affect your rate normally.
It prevents the surcharge from your current carrier, but it doesn't erase the accident from your record. If you switch carriers after using accident forgiveness, the new carrier will see the accident on your CLUE report and may factor it into their pricing. Accident forgiveness keeps your current rate stable. It doesn't make the accident invisible.
Not every carrier offers it, and the terms vary. Some carriers include it automatically for long-term customers. Others charge for it. Some apply it only to minor accidents below a certain claim threshold. Understanding your specific carrier's version of accident forgiveness is important before you count on it.
What Happens When You're Partially at Fault
California's pure comparative negligence system means that fault in an accident can be shared between the drivers involved. You might be found 20 percent at fault while the other driver is 80 percent at fault, or the split might be 50/50.
How partial fault affects your premium depends on the degree of fault assigned to you and your carrier's policies. Under California rules, insurers generally may only surcharge an accident when you were principally at fault, typically meaning more than 50 percent responsible. If you were found only partly responsible, ask your carrier exactly how that was counted.
If you believe the fault determination is wrong, you have the right to dispute it. Start with your insurance company's internal dispute process. If that doesn't resolve the issue, you can file a complaint with the California Department of Insurance. An incorrect fault determination doesn't just affect one claim. It affects your rate for years, so it's worth getting right.
Comprehensive Claims Are Treated Differently
Not all insurance claims are created equal in the eyes of your insurer. Comprehensive claims, those resulting from events like theft, vandalism, weather damage, hitting an animal, or a cracked windshield from road debris, are generally treated more favorably than collision claims.
Because comprehensive events are largely outside your control, most carriers do not surcharge for a single comprehensive claim. You won't see a rate increase because a tree branch fell on your car during a Santa Ana wind event or because your catalytic converter was stolen from a parking lot.
That said, filing multiple comprehensive claims in a short period can draw attention. An insurer may not surcharge each individual claim, but a pattern of claims (three windshields in two years, or two theft claims back to back) may lead to increased scrutiny at renewal or, in some cases, a non-renewal decision.
This distinction is important because it should affect your decision-making. Filing a comprehensive claim for legitimate damage is almost always worthwhile. The risk of a premium impact is low, and the coverage exists precisely for these situations.
When Not Filing a Claim Makes Sense
There are situations where paying for a repair out of pocket rather than filing a claim is the financially smarter move. This isn't about avoiding insurance. It's about understanding when the long-term cost of a claim exceeds the short-term benefit.
When the damage barely exceeds your deductible. If your deductible is $1,000 and the repair estimate is $1,300, you're filing a claim for a $300 benefit. The potential rate increase from that claim could cost you several times that amount over the surcharge period.
When you've already had a recent at-fault accident. A second claim in a short window magnifies the premium impact and may also put you at risk of non-renewal. If the new damage is minor and manageable out of pocket, it may be worth absorbing.
When the damage is cosmetic. A dent or scratch that doesn't affect the vehicle's safety or function is worth considering as an out-of-pocket expense if the alternative is a claim that affects your rate for years.
This isn't a blanket recommendation to avoid filing claims. Insurance exists to protect you from financial loss, and significant damage or injuries should always be reported. But for minor incidents where the claim payout is small, thinking through the long-term cost is a smart use of your time, and your agent can help you run those numbers.
Steps to Minimize the Financial Impact After an Accident
If you've had an at-fault accident and a rate increase is coming, there are concrete steps you can take to manage the impact.
Shop your policy. Different carriers rate accidents differently. The carrier you're with may apply a steeper surcharge than a competitor would for the same incident. Shopping your policy after an accident, not just accepting the renewal increase, can save you hundreds of dollars per year. Some carriers specialize in drivers with imperfect records and may offer significantly better rates.
Increase your deductible. Raising your collision and comprehensive deductibles from $500 to $1,000 reduces your premium. After an accident, this reduction can partially offset the surcharge. Just make sure you can comfortably cover the higher deductible if you need to file another claim.
Review your coverage levels. An accident is a natural trigger for a full policy review. You may be carrying coverage on a vehicle that no longer justifies it, or your liability limits may be due for an adjustment. Optimizing your coverage can reduce your premium even with the accident surcharge in place.
Take a mature driver or defensive driving course. Drivers 55 and older who complete a DMV-approved mature driver course qualify for a discount in California, and some carriers offer discounts for other approved courses. The discount won't erase the accident surcharge, but it can reduce your overall premium.
Maintain a clean record going forward. The most effective long-term strategy is the simplest one. A clean driving record from the date of the accident forward ensures the surcharge drops off on schedule and qualifies you for safe driver discounts once the waiting period ends.
Vetra Insurance Helps You Navigate the Aftermath
An accident is stressful enough without the added anxiety of wondering what it's going to cost you in insurance premiums for the next several years. At Vetra Insurance in El Cajon, we help drivers understand the real financial picture, not the worst-case scenario your imagination comes up with at 2 a.m.
Whether you've just had an accident and want to understand what's ahead, or you're carrying a surcharge from a past incident and want to make sure you're not overpaying, contact Vetra Insurance today or call (619) 630-9091. We'll review your situation, shop your policy across multiple carriers, and make sure you're paying a fair rate for where you are right now, not where you were three years ago.
Related coverage in El Cajon
Get a Free Auto Quote
Talk to a local Vetra Insurance agent in El Cajon. We compare 15+ A-rated carriers to find the right coverage for your situation.